

Auditors say the finished report will identify material weaknesses; financial advisers recommend rolling over short-term debt as state deadlines for free cash and the tax rate close in
By John Barrella
MIDDLEBOROUGH — The town’s fiscal 2025 audit will not be completed in time for Middleborough’s upcoming bond rating call, and when it is finished it will identify internal control weaknesses and material weaknesses, Interim Town Manager Joseph Perkins told the Select Board and Finance Committee in a memorandum dated Aug. 19.
The memo, addressed to both bodies, recounts a telephone call Perkins received Aug. 17 from Zach Nowlan, an auditor, and Scott McIntyre, principal manager at CBIZ, the firm conducting the town’s fiscal 2025 audit. Perkins wrote that the purpose of the call was to inform “those charged with the governance of the Town” of critical issues affecting the audit and causing its delay.
Nowlan and McIntyre described the audit as “significantly challenging” to complete, according to the memo.
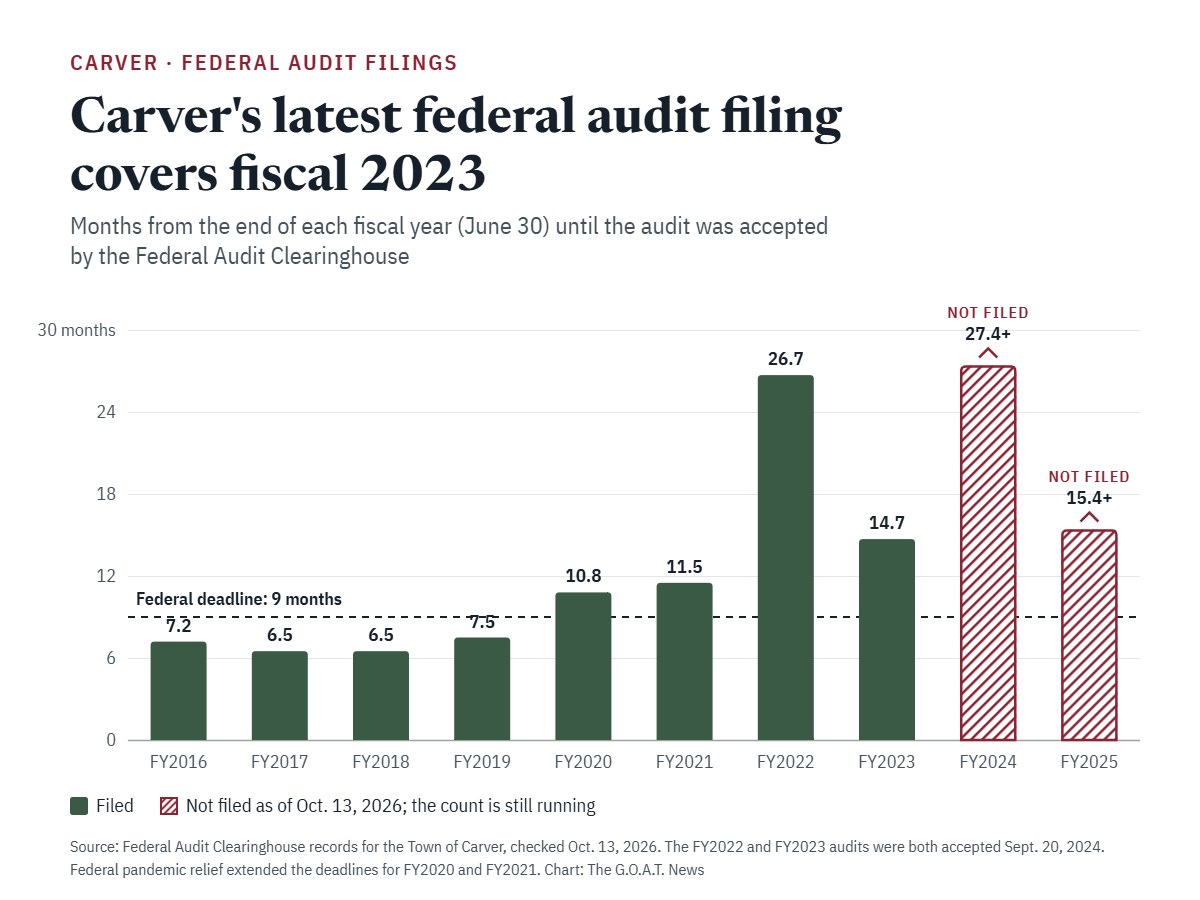
Fiscal 2025 ended on June 30, 2025. The audit is now running more than 13 months behind that close.
The auditors identified four factors behind the delay, Perkins wrote: the town’s change in accounting software in March 2025; a former town employee reporting revenue to the Finance Department in incorrect amounts, along with incorrect data entry; the time required to manually trace and reconcile those reporting errors; and limited staffing at both the town and CBIZ.
CBIZ presented the town two immediate options, according to the memo: permanently finance any debt over a 20-year period, or roll over the town’s Bond Anticipation Notes — short-term borrowing used to fund capital projects until long-term bonds are issued — for three or six months until the audit is complete. Asked which they recommended, the auditors said they could not give that advice and referred the town to its financial adviser, Hilltop Securities.
On Aug. 18, Perkins, Finance Director Sue Nickerson and Treasurer/Collector Erika Correia met by teleconference with Lisa Driscoll and Melissa Toland of Hilltop, the memo states. Hilltop recommended the town roll over its BANs for three to six months to give CBIZ time to finish.
CBIZ also commended Nickerson for her work recreating historical financial data and completing the “debt mapping” of old debt needed to move the audit forward, Perkins wrote.
Reached by telephone, Interim Manager Perkins stated that, “the directive from the audit company (CBIZ) was to inform the individuals charged with the governance of the town”.
What a delayed audit does — and doesn’t — do
The audit delay is not, by itself, a bar to certifying free cash or setting the tax rate. The mechanics matter, and they cut both ways.
Free cash — the unrestricted, unspent balance a community may appropriate — is certified by the state Division of Local Services’ Bureau of Accounts based on an un-audited balance sheet submitted by the municipality. It is not available for use until the accountant submits a June 30 balance sheet and supporting documents and the Director of Accounts certifies the amount.
But the conditions CBIZ describes go to the heart of what the Bureau reviews. Free cash is reduced by reconciling variances in cash and receivables. Misreported revenue and data-entry errors that require manual tracing are precisely the kind of variance that shrinks a certification — or stalls it.
The state has a backstop, too. In her June 2026 year-end letter to municipal accountants, Director of Accounts Deborah A. Wagner wrote that for jurisdictions required to submit audited financial statements before free cash certification, an adverse or disclaimed auditor’s opinion leaves certification to the discretion of the Bureau’s director. Separately, the director may require that after more than two incorrect balance sheet submissions, free cash cannot be certified until the audit is complete and a draft report is filed with the Bureau.
A material weakness finding is not an adverse or disclaimed opinion. But it is the most serious category of internal-control deficiency an auditor can report, meaning a reasonable possibility exists that a material error would not be caught.
State law also requires that audited financial statements be filed with the Director of Accounts within 10 days of the audit report being delivered to the town, under M.G.L. c. 44, § 42.
The calendar
The state’s rate-setting season runs on a fixed schedule, and Middleborough is entering it with its prior fiscal year still unreconciled.
Sept. 30, 2026 — The accountant and treasurer are to submit the June 30 balance sheet to the Bureau of Accounts for free cash certification, along with the Statement of Indebtedness, Treasurer’s Year-End Cash Report, Cash Reconciliation Form and Schedule of Outstanding Receivables.
Oct. 31 — Community Preservation Act fund balance report (CP-2) due.
Nov. 1 — Recommended date for the Select Board’s tax classification hearing, which sets the split between residential and commercial rates.
Nov. 30, 2026 — Assessors submit the Tax Rate Recapitulation Sheet and schedules to the Bureau of Accounts. The same date is the deadline for the town accountant’s Schedule A. Communities that file Schedule A late may have all future local aid payments withheld until it is submitted and accepted.
Dec. 31, 2026 — Statutory deadline for the collector to mail actual tax bills.
That last date is the one with teeth. Before any city or town may assess and collect taxes for a new fiscal year, the Bureau of Accounts must approve its tax rate under M.G.L. c. 59, § 23. When a quarterly-billing community mails actual bills on or before Dec. 31, the balance is payable in two installments, due Feb. 1 and May 1. If the bills go out after Dec. 31, the entire balance becomes payable in a single installment on May 1 — or 30 days after mailing, whichever is later.
For a town already managing a deficit, that would mean losing an entire quarter’s property tax receipt from the winter cash cycle. DLS warns that a late tax rate raises the risk of a temporary cash flow problem that could require short-term internal or external borrowing.
The state has also flagged the specific risk Middleborough is carrying.
Turnover in key positions such as the assessors or auditor-accountant, DLS wrote last year, can create substantial hurdles in completing valuation reports and recap forms. Middleborough has cycled through a town manager departure, an interim appointment and an ongoing search in the same budget year.
Timing is tight even in a normal year. For fiscal 2025, the Bureau approved tax rates for 343 of the state’s 351 municipalities by Dec. 24, 2024, and 262 of those recaps arrived in the final five weeks.
The rating call
The immediate consequence is on the borrowing side. S&P Global Ratings assigned Middleborough’s 2025 general obligation bonds an ‘AA’ rating and its GO bond anticipation notes an ‘SP-1+’ short-term rating on a roughly $12.9 million note issue. At that time S&P noted the town’s $113.3 million fiscal 2026 budget and expectations of continued cautious budgeting practices producing positive variance.
Rating agencies conduct their reviews against audited financials. Going into a rating call without a completed audit — and with advance notice that the audit will disclose material weaknesses — gives analysts less to work with, not more.
Rolling the BANs rather than permanently financing buys the town three to six months. It also means the town returns to the short-term market before the audit is on the table.
Middleborough identified a projected shortfall of roughly $3.38 million during the fiscal 2027 budget rebuild this spring, according to the town’s own budget and operational correction plan, a gap that forced the postponement of Annual Town Meeting from April to June.
The questions now before the Select Board and Finance Committee are narrow and answerable: When does the town expect to submit its June 30, 2026 balance sheet? Has the Bureau of Accounts signaled anything about this year’s certification? What is the target date for the recap? And what is CBIZ’s firm completion date for fiscal 2025?
John Barrella is a member of the Middleborough Finance Committee.
The memo, in it’s entirety can be viewed here:
To: Town of Middleborough Select Board and Town of Middleborough Finance Committee
From: Joseph Perkins, Interim Town Manager, Town of Middleborough
Date: August 19, 2026
RE: FY2025 Audit Status, Identified Challenges, and Financing Recommendation
On Monday, August 17, 2026, I received a telephone call from Zach Nowlan, Auditor, and Scott McIntyre, Principal Manager of CBIZ, the Town of Middleborough’s audit vendor conducting the FY2025 audit.
The purpose of the call was to provide an update on the status of the FY2025 audit and to inform “those charged with the governance of the Town” of critical issues affecting the audit and causing its delay.
Mr. Nowlan and Mr. McIntyre described the audit as “significantly challenging” to complete and informed me that it will not be completed in time for the Town’s upcoming bond rating call.
They identified several factors contributing to the delay, including:
- The Town’s change in accounting software in March 2025.
- A previous Town employee incorrectly reporting revenue to Finance in incorrect amounts and incorrect data entry.
- The significant time required to manually trace and reconcile those reporting errors.
- Limited staffing resources on the part of both the Town and CBIZ.
Mr. McIntyre and Mr. Nowlan identified two immediate options available to the Town:
- Permanently finance any debt over a 20-year period; or
- Roll over the Town’s Bond Anticipation Notes (BANs) for three or six months until the FY2025 audit is completed.
When asked which option they recommended, Mr. McIntyre and Mr. Nowlan stated that they could not provide that advice and recommended that the Town seek guidance from its financial advisor, Hilltop Securities.
CBIZ additionally reported on and commended Finance Director Sue Nickerson for her assistance in recreating historical financial data and completing the “debt mapping” of old debt necessary to advance the audit.
Mr. McIntyre and Mr. Nowlan concluded the call by advising me that the completed FY2025 audit will identify internal control weaknesses and material weaknesses.
On Tuesday, August 19, 2026, Finance Director Sue Nickerson, Town Treasurer Erica Correa, and I participated in a teleconference with Lisa Driscoll and Melissa Toland of Hilltop Securities, the Town’s financial advisors. We discussed the status of the audit and the financing options identified by CBIZ.
Hilltop Securities recommends that the Town roll over its Bond Anticipation Notes (BANs) for a period of three to six months to provide sufficient time for CBIZ to complete the FY2025 audit.
This memorandum is intended to ensure that the Select Board and Finance Committee are informed of the current status of the FY2025 audit, the issues contributing to its delay, the financing options presented by CBIZ, and the recommendation provided by Hilltop Securities.
Sincerely,
Joseph Perkins Interim Town Manager
Leave a Reply